

Trading Education
Day Trading Taxes for Prop Firm Traders: What You Owe
Tax guide for prop firm traders: payout classification, Section 1256 treatment for futures, self-employment tax, deductions, and record-keeping tips.
Source updated
- Originally published
- Source updated
In this article
A prop-firm payout and a gain from a futures contract in your own brokerage account are different transactions. For US federal tax purposes, do not apply Section 1256's futures treatment to a prop reward merely because the simulated trades involved futures.
Start with the contract, the recipient and the payment records. The programme's account name and its displayed trading balance do not determine the tax treatment. This guide addresses US federal concepts; state and non-US rules require separate analysis.
Separate the Two Income Streams
| Record | What it helps establish |
|---|---|
| Personal brokerage statement | Instruments you owned or traded for your own account, gains, losses and fees. |
| Prop-firm agreement | Whether you provide services, participate in a reward arrangement or have another relationship. |
| Payout statement and bank receipt | Gross payment, deductions, payment date and amount received. |
| Tax information form, if issued | What the payer reported, which must be reconciled with the underlying records. |
IRS Form 6781 guidance concerns gains and losses on Section 1256 contracts and straddles. A reward based on another entity's simulated account is not evidence that you personally held such a contract. Have the agreement reviewed before selecting a reporting category.
Contractor Income Is Not a Universal Assumption
Where the facts establish an independent-contractor business, income and qualifying expenses may be reported as business activity, with self-employment tax potentially relevant. Other arrangements need their own classification. A foreign payer's failure to issue a US information form does not by itself remove a reporting obligation.
For contrast, the IRS states that gains from selling securities in a trader's own-account trading business are not subject to self-employment tax. IRS Topic 429 explains this distinction. Calling all trading income “self-employed” can therefore produce the wrong result.
Build a Payout Ledger
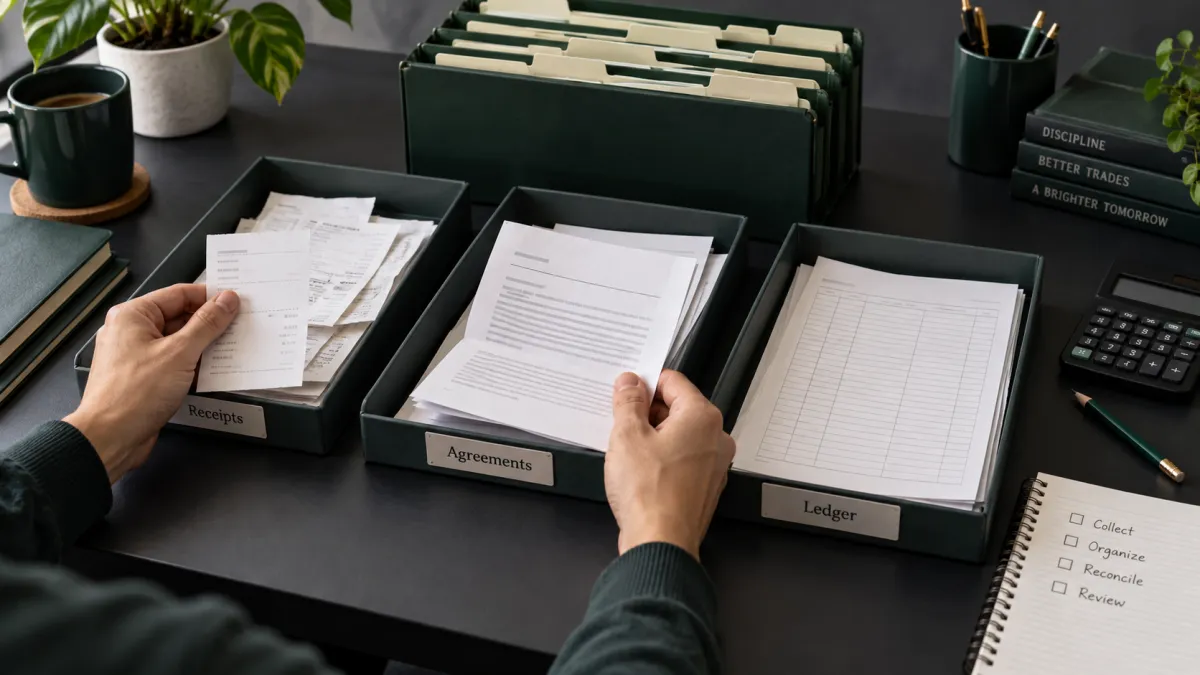
Keep one row per payment with the payer's legal name, contract version, currency, gross reward, withheld or deducted amount, payment-processing charge and date received. Preserve the underlying statement as well as the bank entry.
Keep simulated performance in a separate sheet. It may explain how a reward was calculated, but a displayed account balance is not the same as cash paid to you. If rewards can be approved, cancelled or deferred, retain those events for your adviser to determine the correct accounting treatment.
Fees and Tax Reserves
Save evaluation, reset, activation, data and software invoices. Record the business purpose and any personal use. A receipt proves spending; it does not prove deductibility. Startup, training, equipment and home-office costs each have their own conditions. IRS business-expense resources
Do not use a fixed 25–30% reserve as a promise that your tax bill is covered. Income, deductions, other employment, withholding, filing status and state rules all affect the calculation. Use the IRS estimated-tax worksheet and guidance, with professional help where needed.
Questions to Resolve Before Filing
Ask which income category applies to the actual contract, whether self-employment tax applies, which costs qualify, whether an information form needs correction and whether estimated payments are sufficient. If you also trade a personal account, keep its reporting separate until the proper tax calculations bring the results together.
Frequently Asked Questions
Does trading simulated futures make my payout eligible for 60/40 treatment?
No automatic conclusion follows. Section 1256 concerns qualifying contracts; the tax character of a contractual prop reward must be established separately.
Is every evaluation fee deductible?
No. Keep evidence of the expense and obtain a conclusion based on the activity, purpose and applicable deduction rules.
Should I report the advertised funded account size as income?
An account label is not proof of income received or recognised. Use the agreement and actual payment records to establish what must be reported.
Risk Disclaimer: Trading involves substantial risk of loss. Past performance is not indicative of future results. See our full risk disclaimer.